Free IIA IIA-CIA-Part3 Practice Questions 2026 - Page 16

Ready for IIA-CIA-Part3 Exam?
This practice test is your final exam before the REAL exam
Dare to Take It?
Practice Questions
An organization produces products X and Y. The materials used for the production of both
products are limited to 500 Kilograms
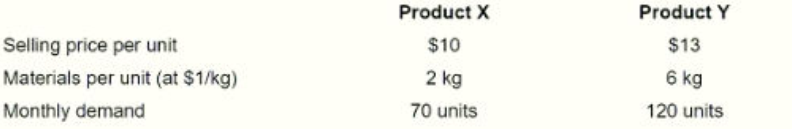
(kg ) per month. All other resources are unlimited and their costs are fixed. Individual
product details are as follows in order to maximize profit, how much of product Y should the
organization produce each month?
$10 $13
2 kg
70 units
6 kg
120 units
A. 50 units
B. 60 units
C. 70 units
D. 1:20 units
Explanation:
When a single resource (materials) is limited and all other resources are unlimited with fixed costs, the organization should maximize profit by producing the product that generates the highest contribution per unit of the scarce resource (materials). First, calculate the contribution per kilogram of material for each product:
Product X: Selling price $10 ÷ 2 kg = $5 per kg
Product Y: Selling price $13 ÷ 6 kg = $2.17 per kg
Since Product X generates a higher contribution per kilogram ($5 vs. $2.17), the organization should first satisfy the full monthly demand for Product X, then use the remaining materials for Product Y.
Materials needed for Product X: 70 units × 2 kg = 140 kg
Materials remaining for Product Y: 500 kg − 140 kg = 360 kg
Units of Product Y that can be produced: 360 kg ÷ 6 kg per unit = 60 units
Therefore, to maximize profit, the organization should produce 70 units of Product X and 60 units of Product Y.
Why the other options are incorrect:
A. 50 units – Producing only 50 units of Product Y would leave 60 kg of material unused (50 × 6 = 300 kg; 360 − 300 = 60 kg remaining). This does not maximize profit because the organization could produce 10 more units of Y with the available material, generating additional contribution.
C. 70 units – Producing 70 units of Product Y would require 420 kg (70 × 6), plus 140 kg for Product X, totaling 560 kg, which exceeds the 500 kg limit. This is not feasible.
D. 120 units – Producing 120 units of Product Y would require 720 kg (120 × 6), far exceeding the 500 kg material limit, and would also leave no material for Product X, which has the higher contribution per kg. This is not feasible and not optimal.
Reference:
* IIA-CIA-Part3 content area on Financial Management / Managerial Accounting – Covers limiting factors, contribution margin analysis, and profit maximization under resource constraints.
Which of the following capital budgeting techniques considers the expected total net cash flows from investment?
A. Cash payback
B. Annual rate of return
C. Incremental analysis
D. Net present value
Explanation:
Net present value (NPV) is a capital budgeting technique that considers the expected total net cash flows from an investment over its entire useful life. It discounts all expected future net cash inflows and outflows back to their present value using a required rate of return (or discount rate) and compares the total present value of inflows against the initial investment. If the NPV is positive, the investment is expected to increase the organization's value and is generally accepted; if negative, it is typically rejected. Because NPV incorporates all expected net cash flows across the project's life and accounts for the time value of money, it is the technique that best reflects the total net cash flows from an investment.
Why the other options are incorrect:
A. Cash payback – The cash payback technique measures how long it takes for an investment to recover its initial cost from net cash inflows. It focuses only on the time required to break even and ignores cash flows that occur after the payback period, so it does not consider the expected total net cash flows from the investment.
B. Annual rate of return – The annual rate of return (also called accounting rate of return) uses accounting net income rather than cash flows and compares average annual income to the average investment. It does not consider total net cash flows and ignores the time value of money.
C. Incremental analysis – Incremental analysis is a general decision-making approach that compares the relevant differences in revenues, costs, and cash flows between alternatives. While it may be used in capital budgeting, it is not a specific capital budgeting technique that systematically evaluates total net cash flows over a project's life in the way NPV does.
Reference:
IIA-CIA-Part3 content area on Financial Management – Covers capital budgeting techniques, including net present value, internal rate of return, payback, and accounting rate of return.
Which of the following networks is suitable for an organization that has operations In multiple cities and countries?
A. Wide area network.
B. Local area network
C. Metropolitan area network
D. Storage area network
Explanation:
A wide area network (WAN) is a network that spans a large geographic area, such as multiple cities, countries, or even continents. It is designed to connect multiple local area networks (LANs) and other networks over long distances, enabling organizations with operations in different locations to communicate, share data, and access centralized resources. WANs typically use leased telecommunication lines, satellites, or internet connections to link geographically dispersed sites, making them the appropriate choice for an organization with operations in multiple cities and countries.
Why the other options are incorrect:
B. Local area network – A local area network (LAN) covers a small geographic area, such as a single building, office, or campus. It is not designed to connect locations across multiple cities or countries, so it is unsuitable for a geographically dispersed organization.
C. Metropolitan area network – A metropolitan area network (MAN) spans a city or a metropolitan region, typically covering an area larger than a LAN but smaller than a WAN. While it can connect multiple locations within a single city, it does not support operations across multiple cities and countries.
D. Storage area network – A storage area network (SAN) is a specialized, high-speed network that provides block-level access to consolidated storage devices. It is used for data storage and retrieval within a data center or among closely located servers, not for connecting geographically dispersed organizational operations.
Reference:
* IIA-CIA-Part3 content area on Information Technology – Covers network types and their appropriate use based on geographic scope.
The internal audit activity has identified accounting errors that resulted in the organization overstating its net income for the fiscal year. Which of the following is the most likely cause of this overstatement?
A. Beginning inventory was overstated for the year.
B. Cost of goods sold was understated for the year.
C. Ending inventory was understated for the year.
D. Cost of goods sold was overstated for the year.
Explanation:
Net income is calculated as revenues minus expenses. Cost of goods sold (COGS) is a major expense on the income statement. If COGS is understated, total expenses are lower than they should be, which causes net income to be overstated. This is one of the most common causes of income overstatement identified in audits. COGS can be understated due to errors such as misclassification of costs, failure to record purchases, or errors in inventory valuation that flow into the COGS calculation.
Why the other options are incorrect:
A. Beginning inventory was overstated for the year – Beginning inventory is added to purchases to determine goods available for sale, and then ending inventory is subtracted to arrive at COGS. If beginning inventory is overstated, COGS would also be overstated, which would cause net income to be understated, not overstated.
C. Ending inventory was understated for the year – Ending inventory is subtracted from goods available for sale to determine COGS. If ending inventory is understated, COGS would be overstated because less is subtracted, which would cause net income to be understated, not overstated. Ending inventory being understated is associated with income understatement.
D. Cost of goods sold was overstated for the year – If COGS is overstated, expenses are higher than they should be, which causes net income to be understated, not overstated. This is the opposite of the situation described in the question.
Reference:
IIA-CIA-Part3 content area on Financial Management / Accounting – Covers the relationship between inventory, cost of goods sold, and net income.
An organization contracted a third-party service provider to plan, design, and build a new facility. Senior management would like to transfer all of the risk to the builder. Which type of procurement contract would the organization use?
A. Cost-plus contract.
B. Turnkey contract.
C. Service contract.
D. Solutions contract.
Explanation:
A turnkey contract is a procurement arrangement in which the organization contracts a third-party provider to plan, design, build, and deliver a fully completed and operational facility or system. Under a turnkey contract, the builder is responsible for the entire project from conception through completion, and the organization simply "turns the key" to take possession of the finished product. Because the builder assumes responsibility for design, construction, performance, and delivery, a turnkey contract transfers the greatest amount of risk to the builder, including risks related to design defects, cost overruns, delays, and performance failures. This makes it the most appropriate contract type when senior management wants to transfer all of the risk to the builder.
Why the other options are incorrect:
A. Cost-plus contract – Under a cost-plus contract, the organization reimburses the contractor for allowable costs plus an agreed-upon profit or fee. This arrangement places most of the cost risk on the organization rather than the builder, because the organization bears the burden of cost overruns. It does not transfer all risk to the builder.
C. Service contract – A service contract is a general agreement for the performance of specific services, such as maintenance, consulting, or support. It does not encompass the full scope of planning, designing, and building a facility, and it does not transfer the comprehensive project risk that a turnkey contract does.
D. Solutions contract – A solutions contract is a broad term sometimes used to describe arrangements where a provider delivers a packaged solution to meet an organization's needs. It is not a standard procurement contract type specifically associated with transferring all design, construction, and performance risk to a builder for a facility project.
Reference:
IIA-CIA-Part3 content area on Business Acumen / Procurement and Contract Management – Covers types of procurement contracts and risk transfer.
According to IIA guidance, which of the following links computers and enables them to - communicate with each other?
A. Application program code
B. Database system
C. Operating system
D. Networks
Explanation:
According to IIA guidance on IT, networks are the components that link computers together and enable them to communicate with each other. A network consists of hardware, software, and transmission media (such as cables, switches, routers, and wireless connections) that allow multiple computers and devices to exchange data, share resources, and communicate across distances. Without a network, computers would operate in isolation and could not share information or resources. This makes networks the correct answer to the question of what links computers and enables communication between them.
Why the other options are incorrect:
A. Application program code – Application program code consists of the instructions and logic that make up software applications, enabling them to perform specific tasks for users. While applications may use a network to communicate, application code itself does not link computers or enable them to communicate with each other.
B. Database system – A database system is a structured collection of data and the software used to manage, store, and retrieve that data (e.g., a database management system). It organizes and provides access to data, but it does not link computers together or serve as the communication mechanism between them.
C. Operating system – An operating system is the software that manages a computer's hardware and provides services for applications (e.g., Windows, Linux). While operating systems include networking capabilities, the operating system itself is not what links computers together; it is the network infrastructure that enables communication between computers.
Reference:
IIA-CIA-Part3 content area on Information Technology – Covers IT infrastructure components, including networks, hardware, software, and databases.
A newly appointed board member received an email that appeared to be from the
company's CEO. The email stated:
“Good morning. As you remember, the closure of projects is our top priority. Kindly
organize prompt payment of the attached invoice for our new solar energy partners.” The
board member quickly replied to the email and asked under which project the expense
should be accounted. Only then did he realize that the sender 's mail domain was different
from the company's. Which of the following cybersecurity risks nearly occurred in the
situation described?
A. A risk of spyware and malware.
B. A risk of corporate espionage.
C. A ransomware attack risk.
D. A social engineering risk.
Explanation:
Social engineering is a cybersecurity risk in which an attacker manipulates people into divulging confidential information, granting access, or performing actions that compromise security, often by impersonating a trusted individual or authority figure. In this situation, the attacker impersonated the CEO using a deceptive email, a tactic known as phishing or business email compromise, and attempted to trick the newly appointed board member into authorizing or processing a fraudulent payment. The board member's reply and near-compliance with the request show how social engineering exploits human trust and authority rather than technical vulnerabilities. The fact that the sender's mail domain was different from the company's is a classic red flag of a social engineering attack.
Why the other options are incorrect:
A. A risk of spyware and malware – Spyware and malware refer to malicious software that is installed on a system to gather information, damage the system, or gain unauthorized access. In this scenario, no malicious software was installed or executed; the attack relied on human manipulation through a deceptive email, which is characteristic of social engineering, not malware.
B. A risk of corporate espionage – Corporate espionage involves the theft of trade secrets, intellectual property, or confidential business information for competitive advantage, often carried out by competitors or state-sponsored actors. While the fraudulent invoice could be a pretext for financial theft, there is no indication in the scenario that the goal was to steal proprietary information, so this is not the best answer.
C. A ransomware attack risk – Ransomware is a type of malware that encrypts a victim's data and demands payment for its release. In this scenario, no data was encrypted and no ransom demand was made; the attacker attempted to trick the board member into making a payment through deception, which is a social engineering tactic, not ransomware.
Reference:
IIA-CIA-Part3 content area on Information Technology – Covers cybersecurity risks, including social engineering, phishing, and business email compromise.
An organization had a gross profit margin of 40 percent in year one and in year two. The net profit margin was 18 percent in year one and 13 percent in year two. Which of the following could be the reason for the decline in the net profit margin for year two?
A. Cost of sales increased relative to sales.
B. Total sales increased relative to expenses.
C. The organization had a higher dividend payout rate in year two.
D. The government increased the corporate tax rate
Explanation:
Net profit margin is calculated as net income divided by sales. It reflects profitability after all expenses, including operating expenses, interest, and taxes, have been deducted. In this scenario, the gross profit margin remained constant at 40 percent in both years, which means the relationship between sales and cost of sales (gross profit) did not change. However, the net profit margin declined from 18 percent to 13 percent, indicating that something below the gross profit line increased. An increase in the corporate tax rate would raise the organization's tax expense, reducing net income while leaving gross profit unchanged, which perfectly explains a decline in net profit margin alongside a stable gross profit margin.
Why the other options are incorrect:
A. Cost of sales increased relative to sales – If cost of sales increased relative to sales, the gross profit margin would have declined. Since the gross profit margin remained constant at 40 percent in both years, this cannot be the reason for the decline in net profit margin.
B. Total sales increased relative to expenses – If total sales increased relative to expenses, net income would increase, and the net profit margin would rise, not decline. This is the opposite of what occurred.
C. The orgCear two – Dividends are distributions of net income to shareholders and are not deducted as an expense in calculating net income. Therefore, a higher dividend payout rate does not affect the net profit margin. It affects retained earnings, not net income.
Reference:
IIA-CIA-Part3 content area on Financial Management – Covers financial ratios, profitability analysis, and the relationship between gross profit margin and net profit margin.
An organization's board of directors is particularly focused on positioning, the organization as a leader in the industry and beating the competition. Which of the following strategies offers the greatest alignment with the board's focus?
A. Divesting product lines expected to have negative profitability.
B. Increasing the diversity of strategic business units.
C. Increasing investment in research and development for a new product.
D. Relocating the organization's manufacturing to another country.
Explanation:
When a board of directors is focused on positioning the organization as an industry leader and beating the competition, the organization is pursuing a strategy centered on competitive advantage, innovation, and market leadership. Increasing investment in research and development (R&D) for a new product aligns best with this focus because it drives innovation, enables the organization to differentiate itself from competitors, and helps it establish or maintain a leading position in the industry. R&D investment supports the development of new products, technologies, and capabilities that can create a competitive edge and strengthen the organization's market position over the long term.
Why the other options are incorrect:
A. Divesting product lines expected to have negative profitability – Divesting unprofitable product lines is a defensive or corrective action aimed at improving financial performance by exiting weak businesses. While it may improve profitability, it does not directly position the organization as an industry leader or help it beat the competition; it is more of a retrenchment strategy.
B. Increasing the diversity of strategic business units – Diversifying strategic business units spreads risk across different markets or products. While diversification can support growth, it does not necessarily position the organization as a leader in its industry or give it a competitive advantage against rivals. It may even dilute focus rather than strengthen competitive positioning.
D. Relocating the organization's manufacturing to another country – Relocating manufacturing is typically a cost-reduction or operational efficiency strategy, such as accessing lower labor costs or new markets. While it may improve margins, it is not primarily aimed at establishing industry leadership or beating competitors through innovation and market positioning.
Reference:
IIA-CIA-Part3 content area on Business Acumen / Strategic Management – Covers business-level strategies, competitive positioning, and the role of innovation in achieving market leadership.
Which of the following items best describes the strategy of outsourcing?
A. Contracting the work to Foreign Service providers to obtain lower costs
B. Contracting functions or knowledge-related work with an external service provider.
C. Contract -ng operation of some business functions with an internal service provider
D. Contracting a specific external service provider to work with an internal service provider
Explanation:
Outsourcing is the practice of contracting business functions, processes, or knowledge-related work to an external service provider rather than performing them internally. The defining characteristics of outsourcing are that the work is performed by a party outside the organization (external provider) and that it can involve a wide range of functions — including operational tasks, IT services, accounting, human resources, customer service, and knowledge-based work such as research, analytics, or consulting. The key element is the transfer of responsibility for a function or process to an external provider, regardless of whether that provider is located domestically or offshore.
Why the other options are incorrect:
A. Contracting the work to Foreign Service providers to obtain lower costs – This describes offshoring, which is a specific form of outsourcing based on geographic location (foreign providers) and cost savings. While offshoring is a subset of outsourcing, the general strategy of outsourcing is not limited to foreign providers or to cost reduction as the sole motivation. This option is too narrow to fully describe outsourcing.
C. Contracting operation of some business functions with an internal service provider – Contracting with an internal service provider (such as a shared services center within the same organization) is not outsourcing. Outsourcing requires the use of an external provider; internal arrangements are considered insourcing or shared services, not outsourcing.
D. Contracting a specific external service provider to work with an internal service provider – This describes a collaborative or hybrid arrangement in which an external provider works alongside an internal provider. While this may involve elements of outsourcing, it does not describe the strategy of outsourcing itself, which is the transfer of a function or process to an external provider, not a joint effort with an internal provider.
Reference:
IIA-CIA-Part3 content area on Business Acumen / Operations Management — specifically outsourcing, offshoring, and the use of external service providers.
| Page 16 out of 69 Pages |