Free IIA IIA-CIA-Part3 Practice Questions 2026 - Page 14

Ready for IIA-CIA-Part3 Exam?
This practice test is your final exam before the REAL exam
Dare to Take It?
Practice Questions
An internal auditor was asked to review an equal equity partnership, in one sampled transaction. Partner A transferred equipment into the partnership with a Self-declared value of 510 ,000, and Partner B contributed equipment with a self-declared value of 515,000. The capital accounts reach partner were subsequently credited with $12,500. Which of the following statements Is true regarding this transection?
A. The capital accounts of the partners should be increased by she original cost of the contributed equipment.
B. The capital accounts should be increased using a weighted average based by the current percentage of ownership.
C. No action is needed, as the capital account of each partner was increased by the correct amount,
D. The capital accounts of the partners should be increased by She fair market value of their contribution.
Explanation:
In partnership accounting, when a partner contributes non-cash assets (such as equipment), the contribution must be recorded at the fair market value (FMV) of the asset on the date of contribution—not the self-declared value, original cost, or book value. The scenario states that Partner A claimed a self-declared value of $510,000 and Partner B claimed $515,000, but both capital accounts were credited with only $12,500—which is clearly erroneous and not based on FMV. The correct accounting treatment is to credit each partner's capital account by the fair market value of the contributed equipment, as this reflects the true economic value brought into the partnership and ensures equitable ownership percentages.
Why the other options are incorrect:
A. The capital accounts of the partners should be increased by the original cost of the contributed equipment. Original cost is historical and does not reflect current value at the time of contribution. Partnership accounting requires fair value, not historical cost.
B. The capital accounts should be increased using a weighted average based by the current percentage of ownership. Weighted average is not used for initial contributions. Each partner's capital is credited based on the value of their individual contribution, not a blended average.
C. No action is needed, as the capital account of each partner was increased by the correct amount. This is false—$12,500 is not the fair market value of either equipment contribution. The amounts are incorrectly recorded.
References:
GAAP / Partnership Accounting – ASC 323: Non-cash contributions to a partnership are recorded at fair value on the date of contribution.
IFRS – IAS 16 & IFRS 13: Assets acquired in exchange or contributed to a partnership are initially measured at fair value.
When would a contract be dosed out?
A. When there's a dispute between the contracting parties
B. When ail contractual obligations have been discharged.
C. When there is a force majenre
D. When the termination clause is enacted
Explanation:
A contract is closed out when both parties have fully performed their respective obligations under the agreement—meaning all deliverables have been provided, all payments have been made, all terms have been satisfied, and there are no remaining duties or claims outstanding. This is the normal, successful conclusion of a contract lifecycle, often referred to as performance or full discharge. At this point, the contract is formally closed, and no further action is required by either party.
Why the other options are incorrect:
A. When there's a dispute between the contracting parties.
A dispute does not close a contract; it typically triggers resolution mechanisms (negotiation, mediation, arbitration, or litigation). The contract remains active until the dispute is resolved and obligations are fulfilled or terminated.
C. When there is a force majeure.
Force majeure (unforeseeable events like natural disasters) may suspend or excuse performance, but it does not automatically close the contract. The parties may renegotiate, wait for the event to pass, or terminate—but closure only occurs when all obligations are discharged or the contract is formally ended.
D. When the termination clause is enacted.
Enacting a termination clause ends the contract early, but this is termination—not normal closure. Termination occurs before full performance and may involve penalties or settlements. Closure is the successful completion of all obligations.
References:
Contract Law (Restatement (Second) of Contracts § 235): A contract is discharged when all duties are fully performed.
CIA Part 3 Syllabus – Legal & Regulatory Issues / Contracting: Tests the candidate's understanding of the contract lifecycle, distinguishing between normal closure (performance/discharge) and early termination.
Which of the following is an indicator of liquidity that is more dependable than working capital?
A. Acid-test (quick) ratio
B. Average collection period
C. Current ratio.
D. Inventory turnover.
Explanation:
Working capital (current assets minus current liabilities) is an absolute dollar amount that does not account for the composition of current assets. It can be misleading because it includes inventory and prepaid expenses, which may not be quickly convertible to cash. The acid-test (quick) ratio is a more dependable indicator of liquidity because it excludes inventory and prepaids, focusing only on cash, marketable securities, and accounts receivable—the most liquid assets that can be used to meet short-term obligations immediately. This ratio provides a stricter, more conservative measure of an organization's ability to pay its current liabilities without relying on the sale of inventory.
Why the other options are incorrect:
B. Average collection period. This measures how quickly receivables are collected. While useful for cash flow analysis, it does not provide a comprehensive liquidity snapshot like the acid-test ratio.
C. Current ratio. The current ratio (current assets ÷ current liabilities) is similar to working capital but is a ratio rather than a dollar amount. However, it still includes inventory and prepaids, making it less dependable than the quick ratio for immediate liquidity assessment.
D. Inventory turnover. This measures how efficiently inventory is sold and replaced. It is an operational efficiency metric, not a direct measure of liquidity.
References:
CIA Part 3 Syllabus – Financial Management / Liquidity Ratios: Tests the candidate's understanding that the acid-test (quick) ratio is a more conservative liquidity measure than the current ratio because it excludes inventory.
Financial Analysis Textbooks (Ross, Brigham): The quick ratio is a more dependable indicator of short-term liquidity as it focuses on the most liquid assets.
An internal auditor found the following information while reviewing the monthly financial
siatements for a wholesaler of safety
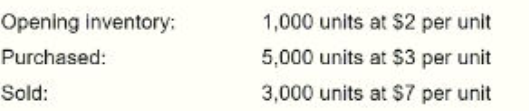
The cost of goods sold was reported at $8,500. Which of the following inventory methods
was used to derive this value?
A. Average cost method
B. First-in, first-out (FIFO) method
C. Specific identification method
D. Activity-based costing method
Explanation:
To determine which inventory method was used, we calculate the Cost of Goods Sold (COGS) under each method and compare it to the reported $8,500.
Given Data:
Opening Inventory: 1,000 units @ $2 = $2,000
Purchases: 5,000 units @ $3 = $15,000
Total Available: 6,000 units @ Total Cost = $17,000
Units Sold: 3,000 units
Average Cost Method:
Weighted Average Cost = $17,000 ÷ 6,000 = $2.8333 per unit
COGS = 3,000 × $2.8333 = **$8,500** ✅
FIFO (First-In, First-Out):
COGS = (1,000 × $2) + (2,000 × $3) = $2,000 + $6,000 = $8,000 ❌
LIFO (Last-In, First-Out):
COGS = 3,000 × $3 = **$9,000** ❌
Since the reported COGS of $8,500 exactly matches the Average Cost method calculation, the wholesaler used the average cost method.
Why the other options are incorrect:
B. FIFO method. FIFO yields $8,000, not $8,500.
C. Specific identification method.
This requires tracking the actual cost of each individual item sold, which cannot be determined from the aggregate data provided.
D. Activity-based costing method.
ABC is a method for allocating overhead costs to products or services, not an inventory costing method for determining COGS.
References:
GAAP – ASC 330 (Inventory): Recognizes average cost, FIFO, LIFO, and specific identification as acceptable inventory costing methods.
CIA Part 3 Syllabus – Financial Management / Inventory Valuation: Tests the candidate's ability to calculate COGS using different inventory methods and identify the method used based on reported figures.
A retail organization mistakenly did have include $10,000 of Inventory in the physical count at the end of the year. What was the impact to the organization's financial statements?
A. Cost of sales and net income are understated.
B. Cost of sales and net income are overstated.
C. Cost of sales is understated and not income is overstated.
D. Cost of sales is overstated and net Income is understated.
Explanation:
When ending inventory is understated (i.e., $10,000 of inventory is not included in the physical count), the Cost of Goods Sold (COGS) is overstated. This is because COGS is calculated as:
COGS = Beginning Inventory + Purchases – Ending Inventory
If Ending Inventory is too low, the subtraction is smaller, making COGS higher (overstated). Higher COGS directly reduces gross profit, which in turn reduces net income. Therefore, net income becomes understated.
This is a classic accounting error with a direct and inverse relationship: understated ending inventory → overstated COGS → understated net income.
Why the other options are incorrect:
A. Cost of sales and net income are understated. This would occur if ending inventory were overstated, not understated.
B. Cost of sales and net income are overstated. This is the opposite of the correct effect. Overstated ending inventory would overstate net income and understate COGS.
C. Cost of sales is understated and net income is overstated. This also describes the effect of an overstated ending inventory, not an understated one.
References:
GAAP – ASC 330 (Inventory): Inventory errors have a direct impact on COGS and net income. An understatement of ending inventory causes COGS to be overstated and net income to be understated.
CIA Part 3 Syllabus – Financial Management / Inventory Errors: Tests the candidate's understanding of the ripple effect of inventory misstatements on financial statements.
Which of the following statements. Is most accurate concerning the management and audit of a web server?
A. The file transfer protocol (FTP) should always be enabled.
B. The simple mail transfer protocol (SMTP) should be operating under the most privileged accounts.
C. The number of ports and protocols allowed to access the web server should be maximized.
D. Secure protocols for confidential pages should be used instead of dear-text protocols such as HTTP or FTP.
Explanation:
When managing and auditing a web server, the most critical security principle is to protect sensitive data during transmission. This is achieved by using secure protocols—such as HTTPS (HTTP over SSL/TLS) for web traffic and SFTP/FTPS for file transfers—instead of clear-text protocols like HTTP or FTP. Clear-text protocols transmit data, including credentials and confidential information, in an unencrypted format, making them vulnerable to interception, eavesdropping, and man-in-the-middle attacks. Secure protocols encrypt the data in transit, ensuring confidentiality and integrity, which is a fundamental control for any web server handling sensitive information.
Why the other options are incorrect:
A. The file transfer protocol (FTP) should always be enabled.
This is false. FTP is a clear-text protocol and should generally be disabled in favor of secure alternatives like SFTP or FTPS. Enabling FTP introduces unnecessary security risks.
B. The simple mail transfer protocol (SMTP) should be operating under the most privileged accounts. This is incorrect and dangerous. Services like SMTP should run under least-privilege accounts, not privileged ones, to minimize the impact if the service is compromised.
C. The number of ports and protocols allowed to access the web server should be maximized. This is the opposite of good security practice. The principle of least functionality dictates that only necessary ports and protocols should be open, reducing the attack surface.
References:
IIA GTAG – Information Security Governance: Emphasizes the use of encrypted protocols (HTTPS, SFTP) to protect data in transit and recommends disabling insecure protocols like HTTP and FTP.
NIST SP 800-53 – SC-8 (Transmission Confidentiality and Integrity): Requires that organizations protect the confidentiality and integrity of transmitted information, typically through encryption.
Which of the following is improved by the use of smart devices?
A. Version control
B. Privacy
C. Portability
D. Secure authentication
Explanation:
Smart devices such as smartphones, tablets, and wearables are characterized primarily by their ability to provide computing functionality while being mobile, that is, their portability. Users can carry them anywhere and still access data, applications, and networks. This is the defining improvement smart devices provide compared with traditional desktop computing.
❌ Why the Other Options Are Incorrect:
A. Version control
– Version control is a function of software tools such as Git and SVN and document management systems. Smart devices do not inherently improve version control. In some cases, editing files across multiple mobile devices can make version management more complex.
B. Privacy
– Smart devices can reduce privacy rather than improve it. They may collect location data, usage patterns, and personal information and can introduce additional privacy concerns. Therefore, privacy is not a defining benefit of smart devices.
D. Secure authentication
– Smart devices can support authentication methods such as biometrics and security tokens, but they also introduce additional attack surfaces and risks. Secure authentication depends on proper implementation and is not an inherent benefit of smart devices.
📚 References:
* IIA-CIA-Part3 – Information Technology – Covers the benefits and risks of emerging technologies, including mobile and smart devices.
* GTAG – Auditing Mobile Computing – Discusses portability as a primary benefit of mobile computing while highlighting associated privacy and security risks.
Which of the following organization structures would most likely be able to cope with rapid changes and uncertainties?
A. Decentralized
B. Centralized
C. Departmentalized
D. Tall structure
Explanation:
A decentralized organizational structure distributes decision-making authority throughout the organization, pushing it down to lower levels of management and closer to where the work occurs. This provides several advantages when facing rapid changes and uncertainties:
Faster decision-making – Decisions do not have to travel through a long chain of command. Local managers can respond quickly to changing conditions.
Greater flexibility and adaptability – Individual units can adjust their operations to local circumstances without waiting for top-level approval.
Empowered employees – Lower-level managers have the authority and autonomy to solve problems as they arise.
Better responsiveness – Those closest to the customer, market, or operational issue can react quickly.
In volatile, complex, or fast-moving environments, this responsiveness provides a decisive advantage.
❌ Why the Other Options Are Incorrect:
B. Centralized – Decision-making authority is concentrated at the top. This can create slower response times because information must flow upward and decisions downward. Centralized structures are better suited to stable, predictable environments where consistency and tight control are more important than speed.
C. Departmentalized – This refers to grouping activities by function, product, geography, or customer. It describes how work is divided, not how authority is distributed. Departmentalization can exist in either centralized or decentralized structures, so it does not directly answer the question about coping with rapid change.
D. Tall structure – A tall hierarchical structure has many layers of management. This lengthens communication channels, slows decision-making, and can create rigidity, which is the opposite of what is needed to cope with rapid changes and uncertainty.
📚 References:
IIA-CIA-Part3 – Business Acumen / Organizational Behavior – Covers organizational structures and their impact on operations, decision-making, and governance.
An organization has an agreement with a third-party vendor to have a fully operational facility, duplicate of the original site and configured to the organization's needs, in order to quickly recover operational capability in the event of a disaster, Which of the following best describes this approach to disaster recovery planning?
A. Cold recovery plan,
B. Outsourced recovery plan.
C. Storage area network recovery plan.
D. Hot recovery plan
Explanation:
A hot site is a fully operational duplicate facility configured to the organization's requirements and capable of being brought online almost immediately in the event of a disaster. It typically includes duplicate hardware, software, network infrastructure, pre-installed applications, replicated or synchronized data, and the resources needed to resume operations. Because it is ready to operate with minimal setup, a hot site provides the fastest recovery time of the recovery-site options, but it is also the most expensive to maintain.
❌ Why the Other Options Are Incorrect:
A. Cold recovery plan – A cold site is an empty or minimally equipped facility with basic infrastructure such as power, HVAC, and cabling, but with no configured hardware or software. It is generally the least expensive option but takes the longest time to become operational, often days or weeks. This is the opposite of the scenario described.
B. Outsourced recovery plan – This describes who manages the recovery capability, typically a third-party provider, rather than the type of recovery facility. Although the scenario involves a third-party vendor, the defining characteristic is the fully operational duplicate facility, which makes it a hot site.
C. Storage area network recovery plan – A SAN is a data storage technology that provides dedicated network access to block-level storage. It can support data replication or recovery operations, but it is not an alternate recovery facility. Therefore, it does not describe the recovery approach in the scenario.
📚 References:
IIA-CIA-Part3 – Business Continuity Management (BCM) and Disaster Recovery Planning – Covers alternate recovery-site strategies, including hot, warm, and cold sites.
Which of the following statements is true regarding the term "flexible budgets" as it is used in accounting?
A. The term describes budgets that exclude fixed costs.
B. Flexible budgets exclude outcome projections, which are hard to determine, and instead rely on the most recent actual outcomes.
C. The term is a red flag for weak budgetary control activities.
D. Flexible budgets project data for different levels of activity.
Explanation:
A flexible budget is a budget that adjusts, or flexes, based on the actual level of activity achieved. Rather than projecting costs and revenues at a single, fixed level of activity, as a static budget does, a flexible budget presents figures for multiple levels of activity, such as different production or sales volumes. This allows management to compare actual results against the budgeted amounts that should have occurred at the actual activity level, making performance evaluation more meaningful.
For example, if a company budgeted for 10,000 units but actually produced 12,000 units, a static budget comparison could be misleading. A flexible budget recalculates expected costs for 12,000 units, allowing variances to reflect actual performance rather than differences in activity levels.
❌ Why the Other Options Are Incorrect:
A. The term describes budgets that exclude fixed costs – This is incorrect. Flexible budgets nclude both fixed and variable costs. Fixed costs remain constant across activity levels, while variable costs change proportionally. The flexible budget accounts for both types of costs when showing how total costs behave at different activity levels.
B. Flexible budgets exclude outcome projections, which are hard to determine, and instead rely on the most recent actual outcomes – This is incorrect. Flexible budgets are still projections or plans. They are prepared using expected cost behavior, such as fixed costs plus variable cost per unit multiplied by the activity level. They do not simply rely on past actual outcomes. Using only recent actuals would represent a different budgeting approach.
C. The term is a red flag for weak budgetary control activities – This is incorrect. Flexible budgets are actually a strength in budgetary control, not a weakness. They enhance control by enabling fair and accurate variance analysis at the actual activity level. The absence of flexible budgeting or consistently unexplained large variances may indicate weaknesses in budgetary control.
📚 Reference:
* IIA-CIA-Part3 – Financial Management / Managerial Accounting – Covers budgeting concepts and techniques, including static and flexible budgets.
| Page 14 out of 69 Pages |